
*Please note there will be a delay in the reflection of pricing trends at local distributors, attributed to the timing of inventory turnover and the arrival of new stock at distribution centers.
October marks the transition from summer menus into fall comfort food, Thanksgiving, hockey and football season. For independent operators, that shift is arriving with an unusually wide gap between expensive and value-priced proteins.
For operators, October is less about finding one universally inexpensive protein and more about moving menu emphasis toward the categories currently offering value while controlling exposure to those that remain expensive.
Beef Insights
What’s Happening?
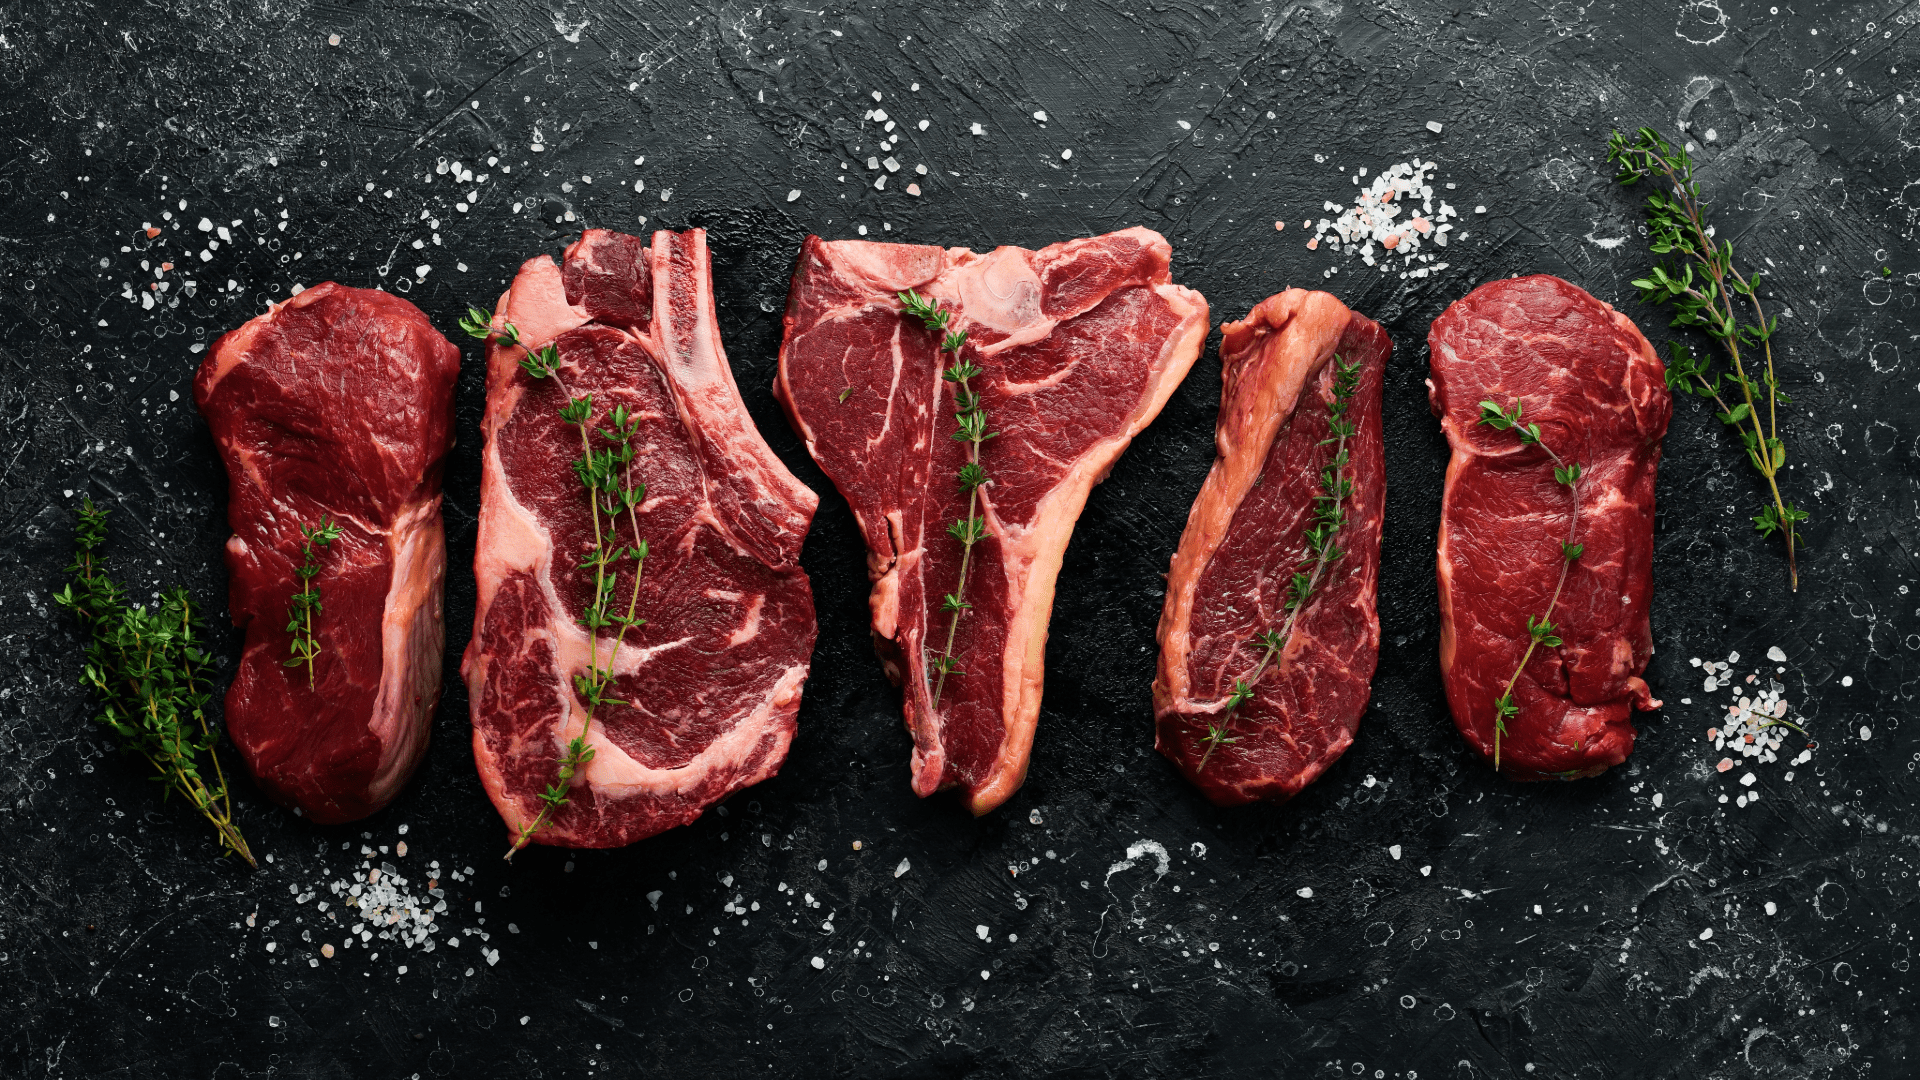
Beef remains a complicated market. Reduced production provided short-term support to wholesale prices, but the important question is whether those values hold as processing returns toward normal levels. The market is also becoming increasingly divided by cut.
Ribs and loins remain expensive as foodservice demand moves into the fall. Rib values typically strengthen further as holiday prime-rib demand approaches. This is not where operators should expect significant relief. Ground beef is different. Fat and lean trim values have recently weakened, including a particularly sharp decline in fresh 85% lean trim. That creates an opportunity for burger programs and other ground-beef applications.
Rounds, clods and other value-oriented cuts may also provide buying opportunities. These cuts become more useful operationally as menus transition toward roast beef, braised beef and other fall applications.
The longer-term beef story, however, has not changed: North American cattle supplies remain tight, so temporary corrections should be viewed as buying opportunities rather than evidence that inexpensive beef has returned. Check our chart for individual cut pricing trends.
What Can You Do?
Recent trim declines could materially improve burger costs.
Look at rounds and clods for roast beef, sandwiches, bowls and braised applications.
Be cautious with loin and rib purchases; premium middle meats remain expensive.
Menu Suggestions
Slow-Roasted Beef Dip with Caramelized Onions
Beef & Mushroom Pot Pie
Smash Burger with Bacon-Onion Jam
Pork Insights
What’s Happening?
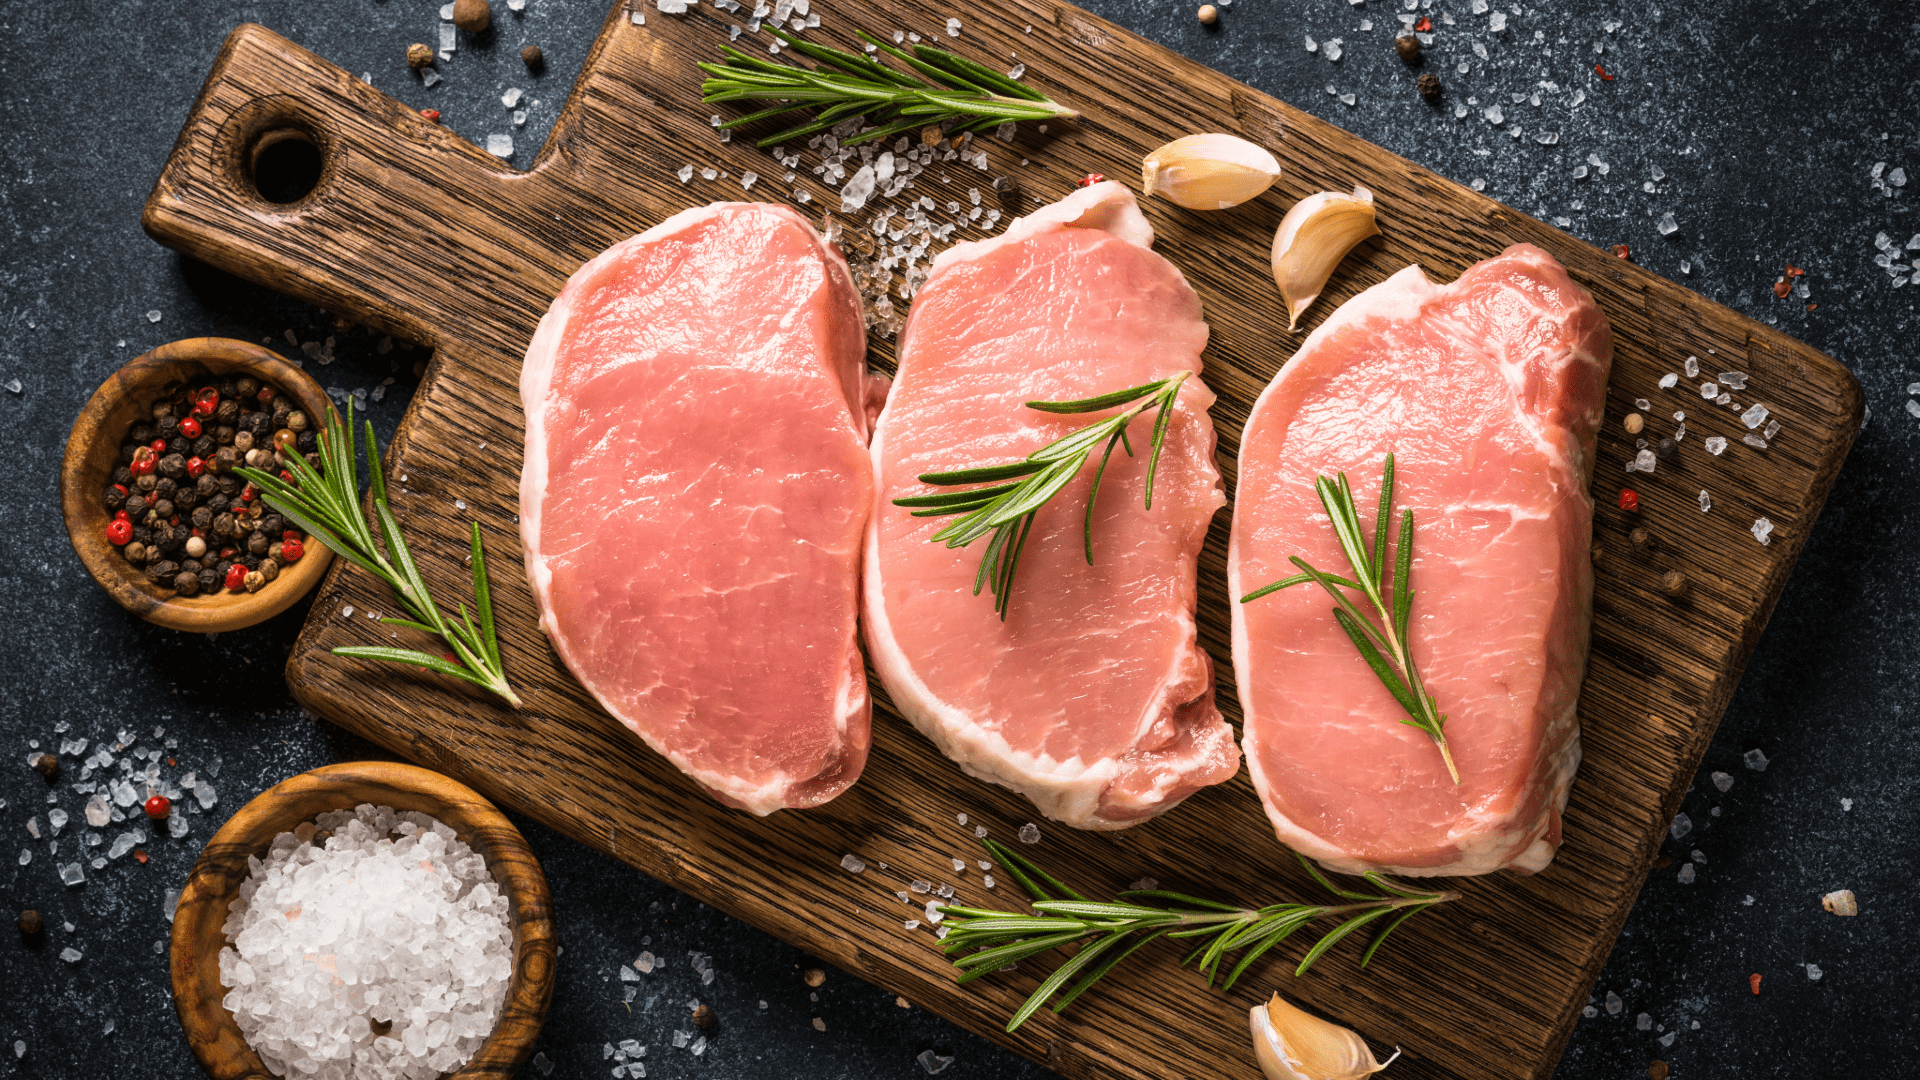
Pork is the protein category operators should be paying particularly close attention to this month. The pork market has weakened considerably since summer. Recent cutout values have fallen approximately 20% below last year’s levels according to the broker information.
The underlying reason is relatively straightforward: supplies are comfortable while domestic and export demand have remained disappointing. Pork demand is weaker than normal and identifies increasing autumn supply, cautious consumer spending and softer exports as continuing downside risks. Canadian production is not contracting either and is now3–4% above 2025.
Bellies have experienced one of the largest corrections, creating a much better bacon environment than operators faced earlier in the year. Ribs are also softening as grilling demand disappears.
Butts and picnics remain excellent candidates for fall comfort-food menus, while loin pricing has begun to firm somewhat as buyers secure forward coverage. Hams are another category worth watching: they have strengthened from depressed levels and should receive additional seasonal support as holiday buying develops. Check our chart for individual cut pricing trends.
What Can You Do?
Make pork a featured protein, not merely a substitute for beef.
Review bacon costs now following the correction in belly markets.
Use butts and picnics for pulled pork, carnitas and batch-cooked applications.
Menu Suggestions
Apple-Cider Braised Pork with Mashed Potatoes
Pulled Pork Mac & Cheese
Maple-Mustard Pork Loin
Poultry Insights
What’s Happening?
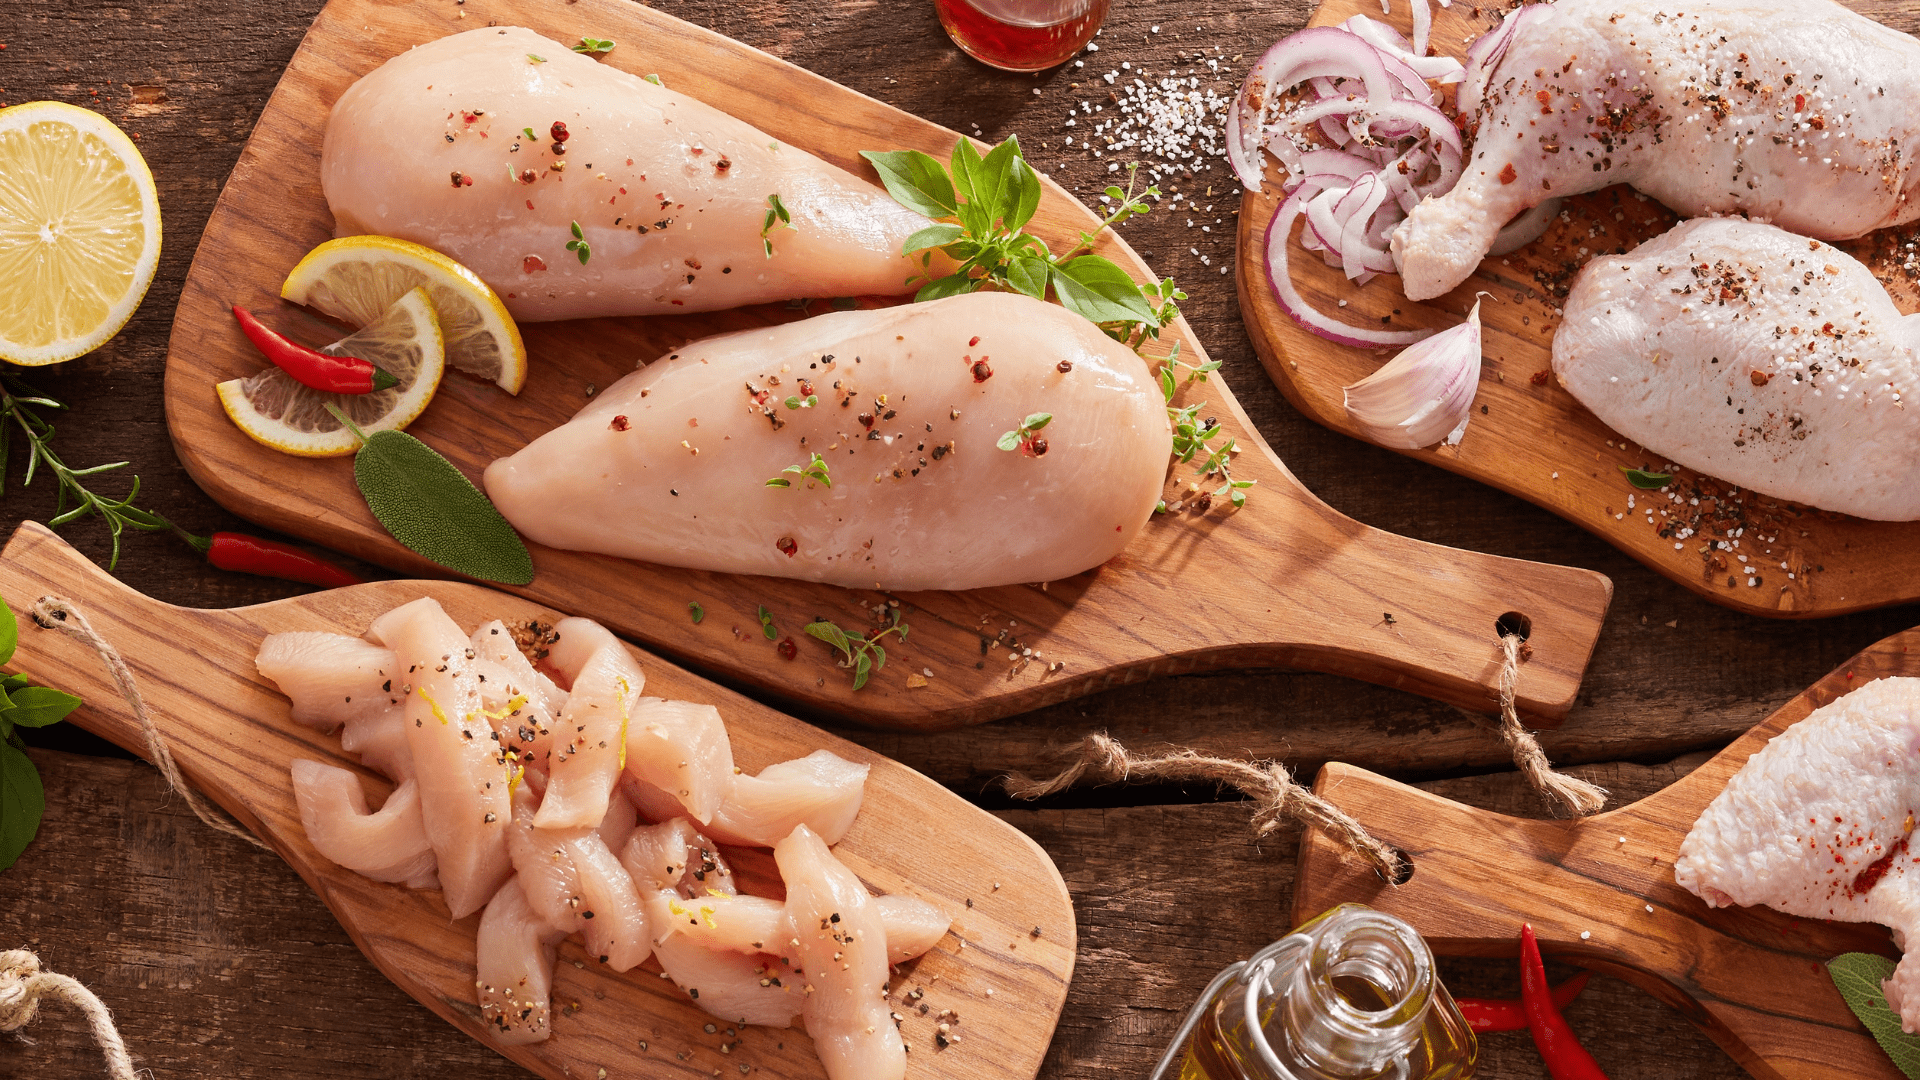
Chicken requires a distinctly Canadian perspective. Canadian chicken demand remains exceptionally strong despite historically high retail and wholesale prices. August Canadian production reached 131.4 million kg—the largest monthly production total on record and 4.6% above the previous year. Even with that record production, prices declined only modestly because demand remained strong.
Availability has nevertheless improved. Boneless breast is more readily available, wings are adequate, drums have loosened, while thighs supply is tighter. Breast prices have started their normal seasonal decline and wings moved lower through August. Canadian legs remain unusually expensive relative to historical averages.
The U.S. market is substantially softer. As of late September boneless breast and tenderloin pricing is declining while wings are flat, with analysts expecting generally balanced supply through year-end.
That doesn’t mean Canadian operators receive U.S. pricing. Supply management, quota availability, exchange rates and a Canadian dollar near 1.42 all limit the pass-through. Check our chart for individual cut pricing trends.
What Can You Do?
Requote breast and wing products as availability improves.
Don’t assume thighs are the economical alternative. Current leg pricing remains elevated.
Wings remain worth evaluating for hockey and football promotions.
Menu Suggestions
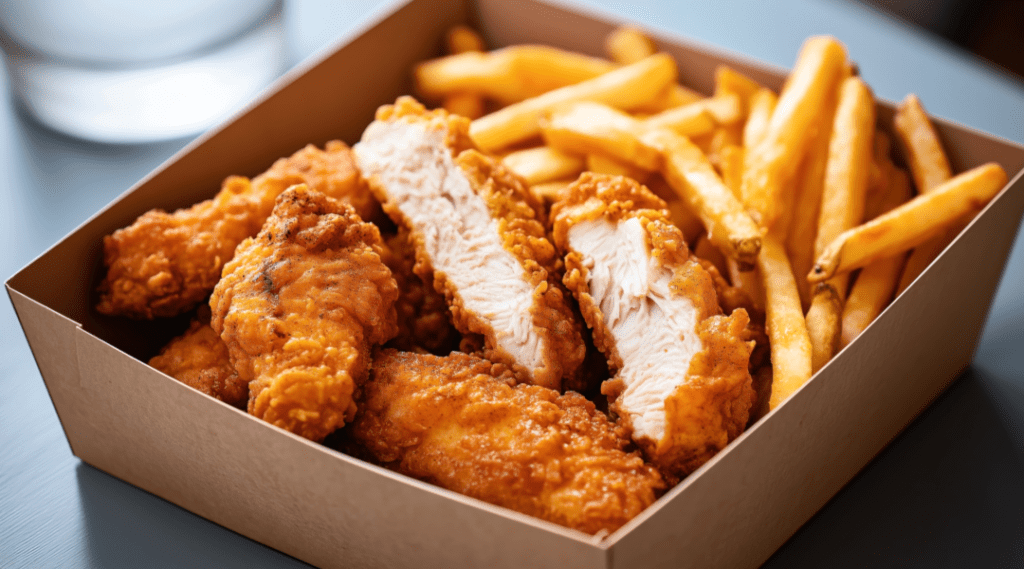
Hot Honey Chicken Sandwich
Garlic-Parmesan Wings
Buffalo Chicken Mac & Cheese
Seafood Insights
What’s Happening?
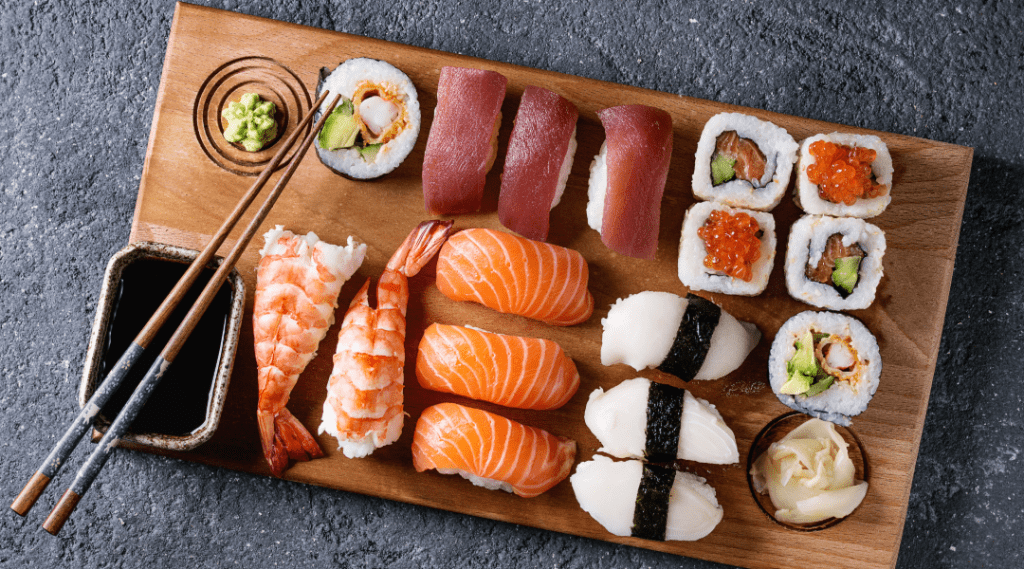
Seafood is relatively stable entering October, but there are several useful opportunities for independent operators. Imported Black Tiger Shrimp is one of them. There is lower pricing reported across imported Black Tigers and whites. That continues the improvement we identified last month and makes shrimp increasingly interesting for operators who can tightly control portions.
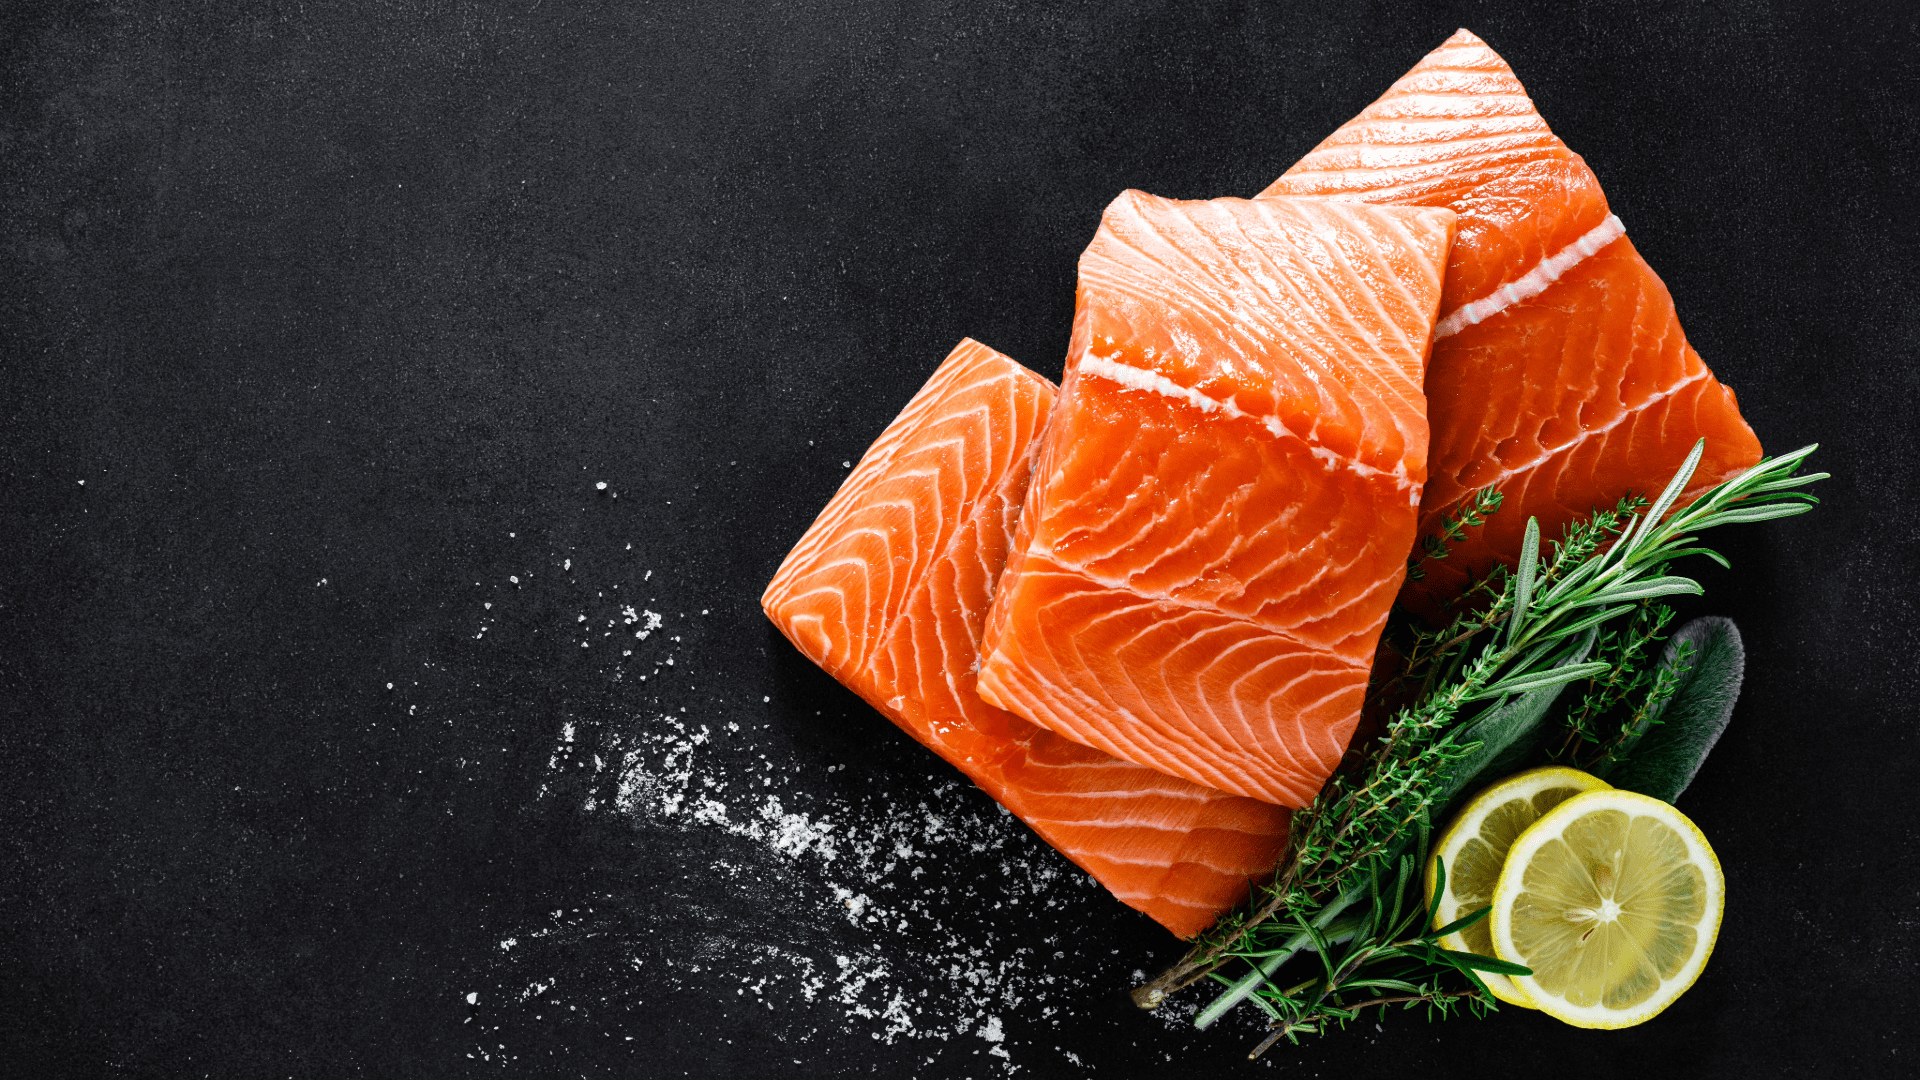
Atlantic salmon is more mixed. After falling considerably from the extreme pricing experienced in previous years, salmon remains a more practical menu option than it was two years ago. Current markets vary by origin and specification, so operators should continue quoting fresh and frozen alternatives rather than assuming one salmon market. For traditional fish applications, pollock pricing is steady but supplies have tightened due to increased demand, while haddock pricing is also steady with constrained supply.
That makes specification flexibility increasingly important. Cod, haddock and pollock can all work in appropriate applications, but operators should compare delivered cost, portion size, yield and guest expectations rather than automatically purchasing the same species every month.
What Can You Do?
Requote Black Tiger Shrimp—the recent decline creates feature opportunities.
Portion shrimp by count to maintain consistent plate costs.
Continue comparing fresh versus frozen Atlantic salmon.
Menu Suggestions
Black Tiger Shrimp Linguine with Garlic & Chili
Maple-Dijon Atlantic Salmon with Roasted Vegetables
Blackened Haddock Tacos with Chipotle Slaw
Produce Insights
What’s Happening?
The produce market is entering one of its more challenging transition periods. The clearest problem is asparagus. Production from imports remain well below demand so expect significantly higher pricing, size restrictions and tight supplies extending into early 2027.
Lettuce is another category to watch. Iceberg prices are escalating as yields decline, with green leaf and romaine also moving higher. This is important because lettuce is a high-volume ingredient with relatively little opportunity to recover sudden increases through menu pricing.
Broccoli is strengthening as tight supply and insect pressure reduce yields, while cauliflower remains elevated. Limes remain tight and quality is inconsistent following heat, humidity and rain. Small oranges also remain tight. There are, however, useful opportunities. Avocado stocks are relatively plentiful, grapes remain abundant, strawberries have softened as production improves, and celery is currently inexpensive with excellent availability.
The late-September reports also highlight potential weather disruption from Hurricane Polo for Mexican avocados and limes, with possible effects on cucumbers, squash and tomatoes depending on rainfall.
What Can You Do?
Monitor lettuce yields and salad food costs weekly.
Avoid over-ordering berries simply because pricing improves—shelf life remains critical.
Take advantage of avocado availability for burgers, sandwiches, bowls and Mexican-inspired features.
Price Alerts as of October 1, 2026
Watch: Asparagus, iceberg lettuce, romaine, green leaf, broccoli, blueberries, limes, squash and large russet potatoes.
Better-value opportunities: Avocados, grapes, strawberries, celery and selected seasonal apples.
Bell peppers deserve special attention: green markets are currently relatively steady, but expect upward pressure.
Consider Frozen with Alasko!
When fresh supply is volatile or labour is tight, Alasko frozen fruits and vegetables deliver consistent quality and predictable cost control.