
*Please note there will be a delay in the reflection of pricing trends at local distributors, attributed to the timing of inventory turnover and the arrival of new stock at distribution centers.
Beef Insights
What’s Happening?
Beef remains the most difficult protein market despite the correction seen earlier this summer. Boxed beef has begun strengthening again, with ribs, loins and briskets have been among the stronger priced primals as early fall positioning begin. The larger concern is structural.
Tyson Foods has announced another major restructuring of its U.S. beef operations. The closure of some of their operations are not happening because beef demand has collapsed. They are happening because North American cattle supplies remain historically tight and packers are struggling to operate plants profitably.
For restaurant operators, that reinforces an important message: the summer correction in beef should not be interpreted as the beginning of a long period of inexpensive beef. Check our chart for individual cut pricing trends.
What Can You Do?
Review Fall and holiday beef requirements now rather than waiting until November.
Take advantage of tactical opportunities when individual cuts soften.
Build fall beef features around chuck, round and braised applications where the economics work.
Menu Suggestions
Slow-Roasted Beef Dip with Au Jus
Braised Beef & Mushroom Pot Pie
Beef Short Rib Poutine
Pork Insights
What’s Happening?
Pork continues to be the strongest value story in the protein market heading into fall. Overall pork supplies are gradually increasing seasonally, but demand remains uneven. Bellies and hams have seen a recent increase in prices, while loins and butts continue to provide excellent value.
Loins remain particularly attractive. They are well below many historical relationships with beef and chicken and offer operators an opportunity to create a generous-looking centre-of-plate meal without the food cost associated with steak.
Bellies are the category to watch. Strong bacon demand has supported prices through late summer, and operators should not assume the lower belly values available earlier this year will continue indefinitely. Hams are also receiving seasonal support as buyers begin positioning for fall and holiday programs. Check our chart for individual cut pricing trends.
What Can You Do?
Make pork loin one of your primary fall feature proteins.
Use butts for pulled pork, carnitas and other batch-cooked applications.
Review bacon specifications and portion sizes as belly prices strengthen.
Menu Suggestions
Pork Schnitzel Sandwich with Dijon Mayo
Apple Cider Braised Pork
Korean BBQ Pork Rice Bowl
Poultry Insights
What’s Happening?
Chicken may be developing into one of the more interesting protein opportunities heading into fall. U.S. poultry producers expanded production significantly over the past year in anticipation that consumers would shift away from expensive beef. Beef demand remained stronger than expected, leaving the U.S. chicken industry with considerably more product available. That has pushed U.S. wholesale prices lower, particularly for boneless breast meat, wings and some other high-volume cuts.
The Canadian market operates differently because of supply management, so Canadian operators should not expect U.S. wholesale declines to transfer dollar-for-dollar into their delivered cost. However, increased North American supply should reduce some of the pressure that operators experienced during 2025 and early 2026.
This makes September a good time to revisit chicken specifications and pricing with distributors. Check our chart for individual cut pricing trends.
What Can You Do?
Requote breast, wing and tender specifications rather than assuming existing prices remain competitive.
Consider football-season wing features if delivered costs support them.
Use improved chicken costs to rebuild margin before lowering menu prices.
Menu Suggestions
Buffalo Wings with House Blue Cheese Dip
Hot Honey Chicken Sandwich
Crispy Chicken Caesar Wrap
Seafood Insights
What’s Happening?
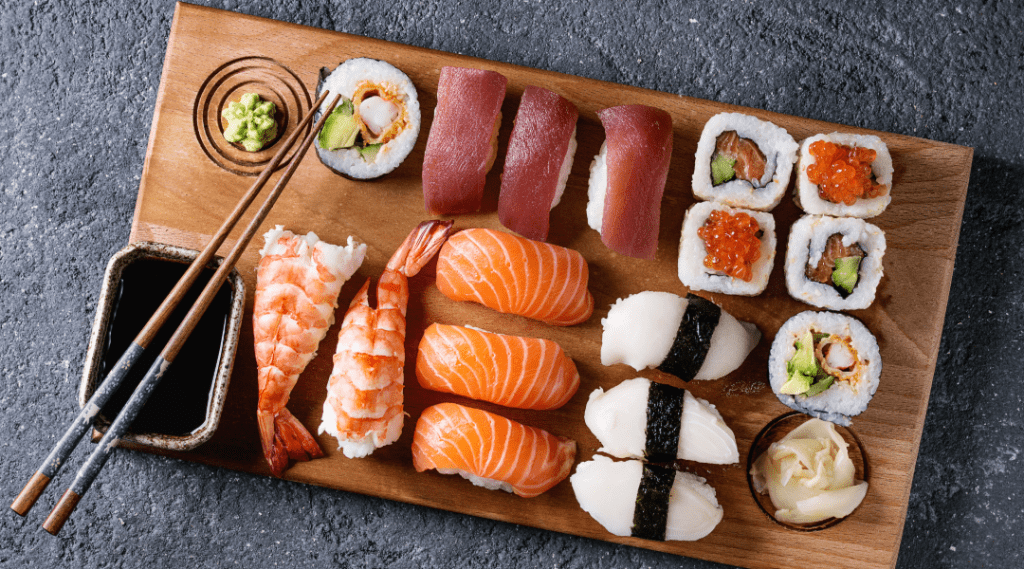
Seafood continues to offer more price stability than beef, but individual species are moving in very different directions. Global salmon prices are substantially below the extreme levels seen two years ago. Comparable Norwegian Atlantic salmon pricing this summer has been roughly 8% below 2025 and approximately 18% below 2024 levels. That creates better opportunities for salmon than operators have seen during several previous menu cycles.
However, the market appears to be turning. Fresh Chilean salmon has recently begun moving higher, while frozen Atlantic salmon portions are relatively stable. The Canadian dollar also remains important because much of the salmon used in Canadian foodservice is internationally priced. For operators who removed or reduced salmon because of earlier pricing, it may be worth revisiting, but portion control remains essential.
Black Tiger Shrimp has followed a different path. Shrimp markets have been far more stable over the past two years than salmon. Imported Black Tiger pricing softened during July and has recently stabilized as new inventory reaches North America.
That makes shrimp an attractive menu ingredient, especially where operators can control the number of shrimp used per serving. Cod, haddock and pollock also remain dependable options for independent operators, particularly in frozen portion-controlled formats that minimize labour and waste.
What Can You Do?
Consider Black Tiger Shrimp for premium shrimp applications while pricing remains relatively stable.
Control shrimp portions by count rather than weight during service.
Use cod, haddock and pollock in frozen portion-controlled formats for predictable food cost.
Menu Suggestions
Maple-Dijon Atlantic Salmon with Roasted Vegetables
Black Tiger Shrimp Linguine with Garlic and Chili
Blackened Haddock Tacos with Pineapple Slaw
Produce Insights
What’s Happening?
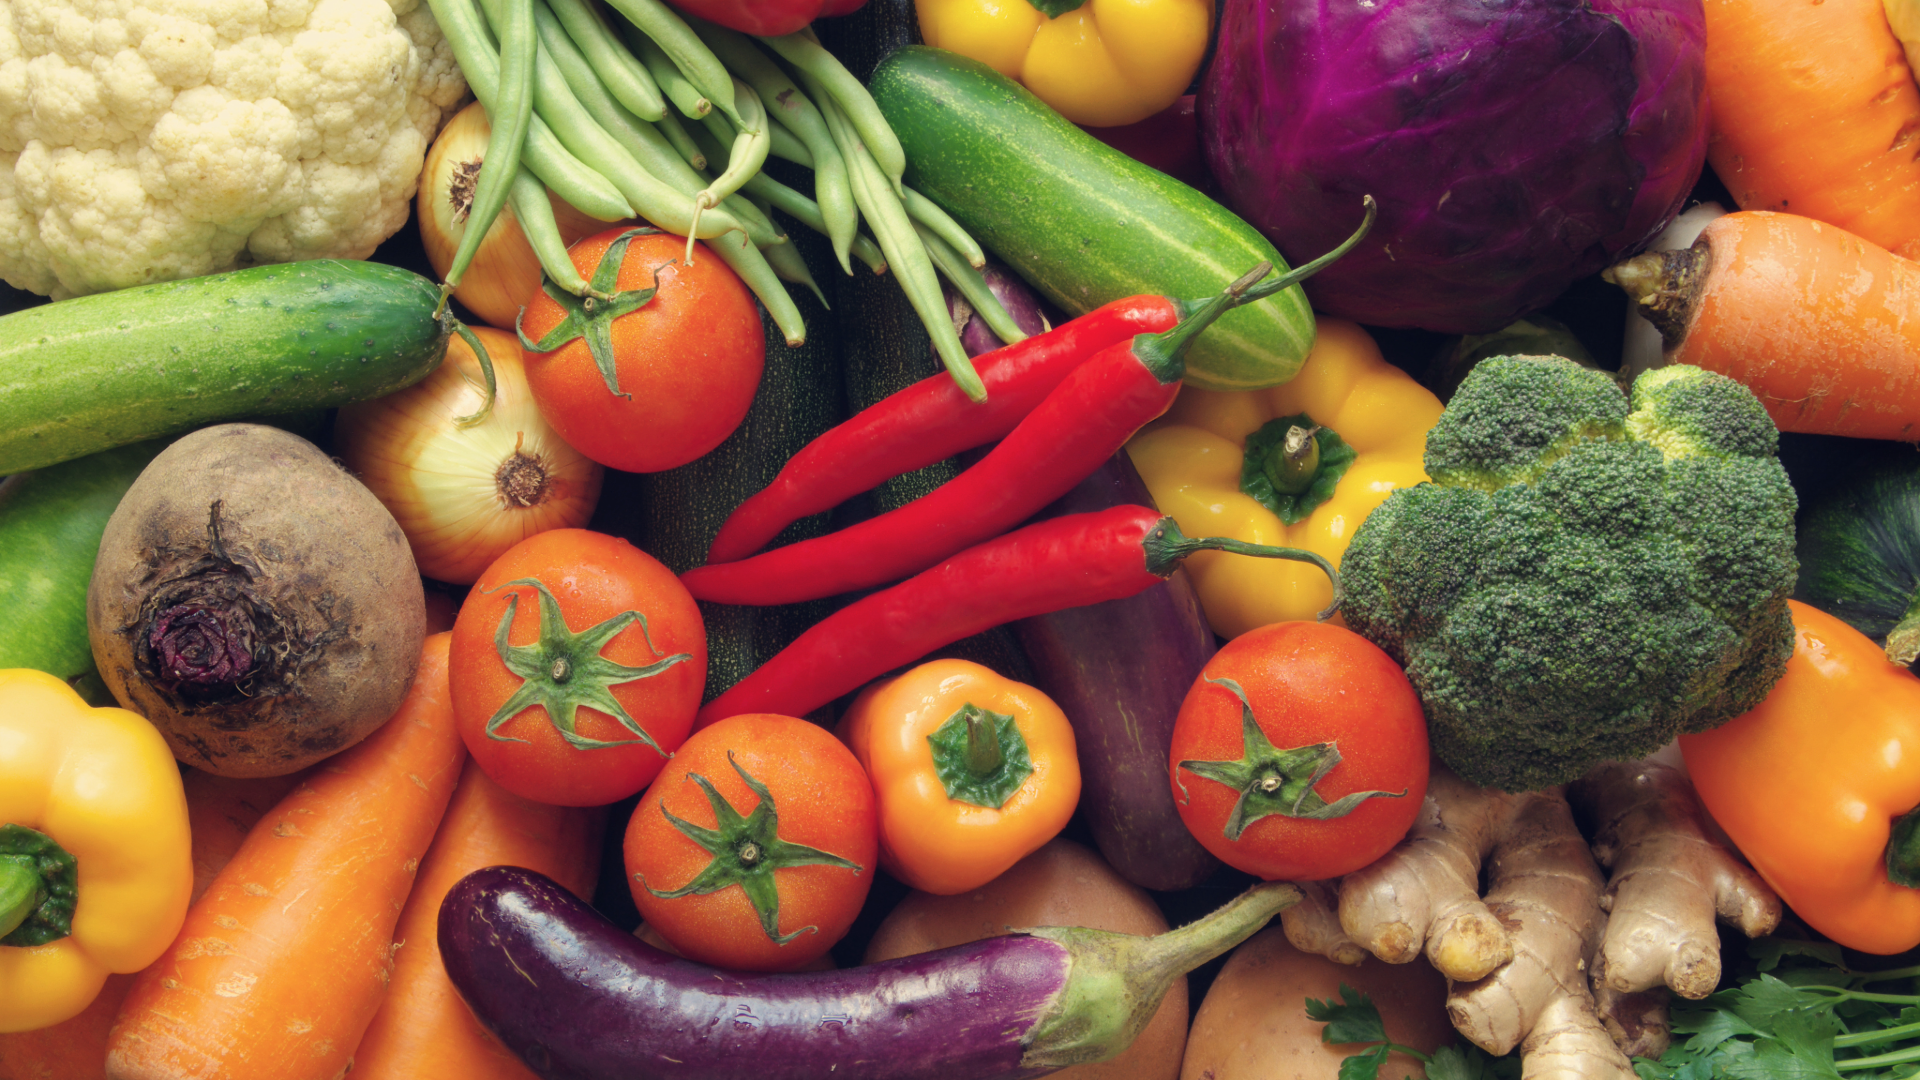
Produce markets entering September are unusually divided between excellent seasonal buying opportunities and several products that remain very expensive. After becoming one of the biggest produce inflation stories earlier this year, conventional field tomato markets are now low as summer supplies remain abundant across California, Mexico and several eastern growing regions. This is an excellent example of why operators need to follow produce markets rather than simply accepting the pricing conditions experienced earlier in the year.
Green and red bell pepper markets are also weak, cauliflower is beginning to ease, and domestic grape and melon supplies are abundant. Cantaloupe, honeydew and grapes currently provide attractive value for catering, breakfast, salads and desserts. Onions are another good fall value as new-crop production expands.
The expensive side of the market includes asparagus, limes and lemons. Strawberries are also strengthening as summer production declines.
Russet potatoes need watching. Larger 40- through 70-count potatoes are expected to strengthen during the transition to new crop, although smaller potatoes and several alternative varieties provide better availability. Lettuce markets are generally manageable, although heat-related quality problems remain possible.
What Can You Do?
Take advantage of lower tomato pricing while summer supplies remain abundant.
Use tomatoes aggressively in seasonal features while the value opportunity lasts.
Lean into peppers, grapes, melons, cauliflower and onions where pricing is favourable.
Price Alerts as of September 1, 2026
Asparagus: very high markets; little near-term relief.
Limes: supplies tightening and prices rising.
Lemons: pricing remains high.
Strawberries: lower production is pushing prices higher.
Broccolini: supply gaps following summer heat.
Avocados: larger fruit remains firm.
Better-Value Produce Opportunities
Tomatoes: abundant summer supplies and low markets.
Green & Red Peppers: strong production and weak pricing.
Grapes: plentiful domestic supply and low prices.
Cantaloupe & Honeydew: excellent supply and attractive pricing.
Cauliflower: increasing availability.
Onions: new-crop supplies providing good value.
Broccoli: increasing supply and stabilizing pricing.
Consider Frozen with Alasko!
When fresh supply is volatile or labour is tight, Alasko frozen fruits and vegetables deliver consistent quality and predictable cost control.